
What Rising Mortgage Rates Above 7% Mean for Housing and Your Finances

The housing market plays a major role both in people's personal lives and in the overall health of the economy. For most families, buying a home takes years of saving and planning. A home is often the biggest asset a family owns, the largest monthly bill they pay, and the main source of money they have borrowed. Beyond individual households, housing is also a significant part of the national economy, making up between 15% and 18% of total economic activity.1 Because so many people's financial well-being is tied to housing, shifts in the housing market can affect how confident consumers feel, the overall financial health of households, and how fast the economy grows.
One of the most important factors shaping the housing market is interest rates. When interest rates go up, the cost of getting a mortgage (a home loan) goes up too. This affects everything from whether someone qualifies for a loan to how many homes are bought and sold. The average rate on a 30-year fixed mortgage (a home loan with the same interest rate for 30 years) has climbed back above 7%, after briefly dropping toward 6% earlier this year. Mortgage rates have moved around a lot recently, but rates at this level have not been seen consistently for nearly 25 years. What does this mean for families and the broader economy?
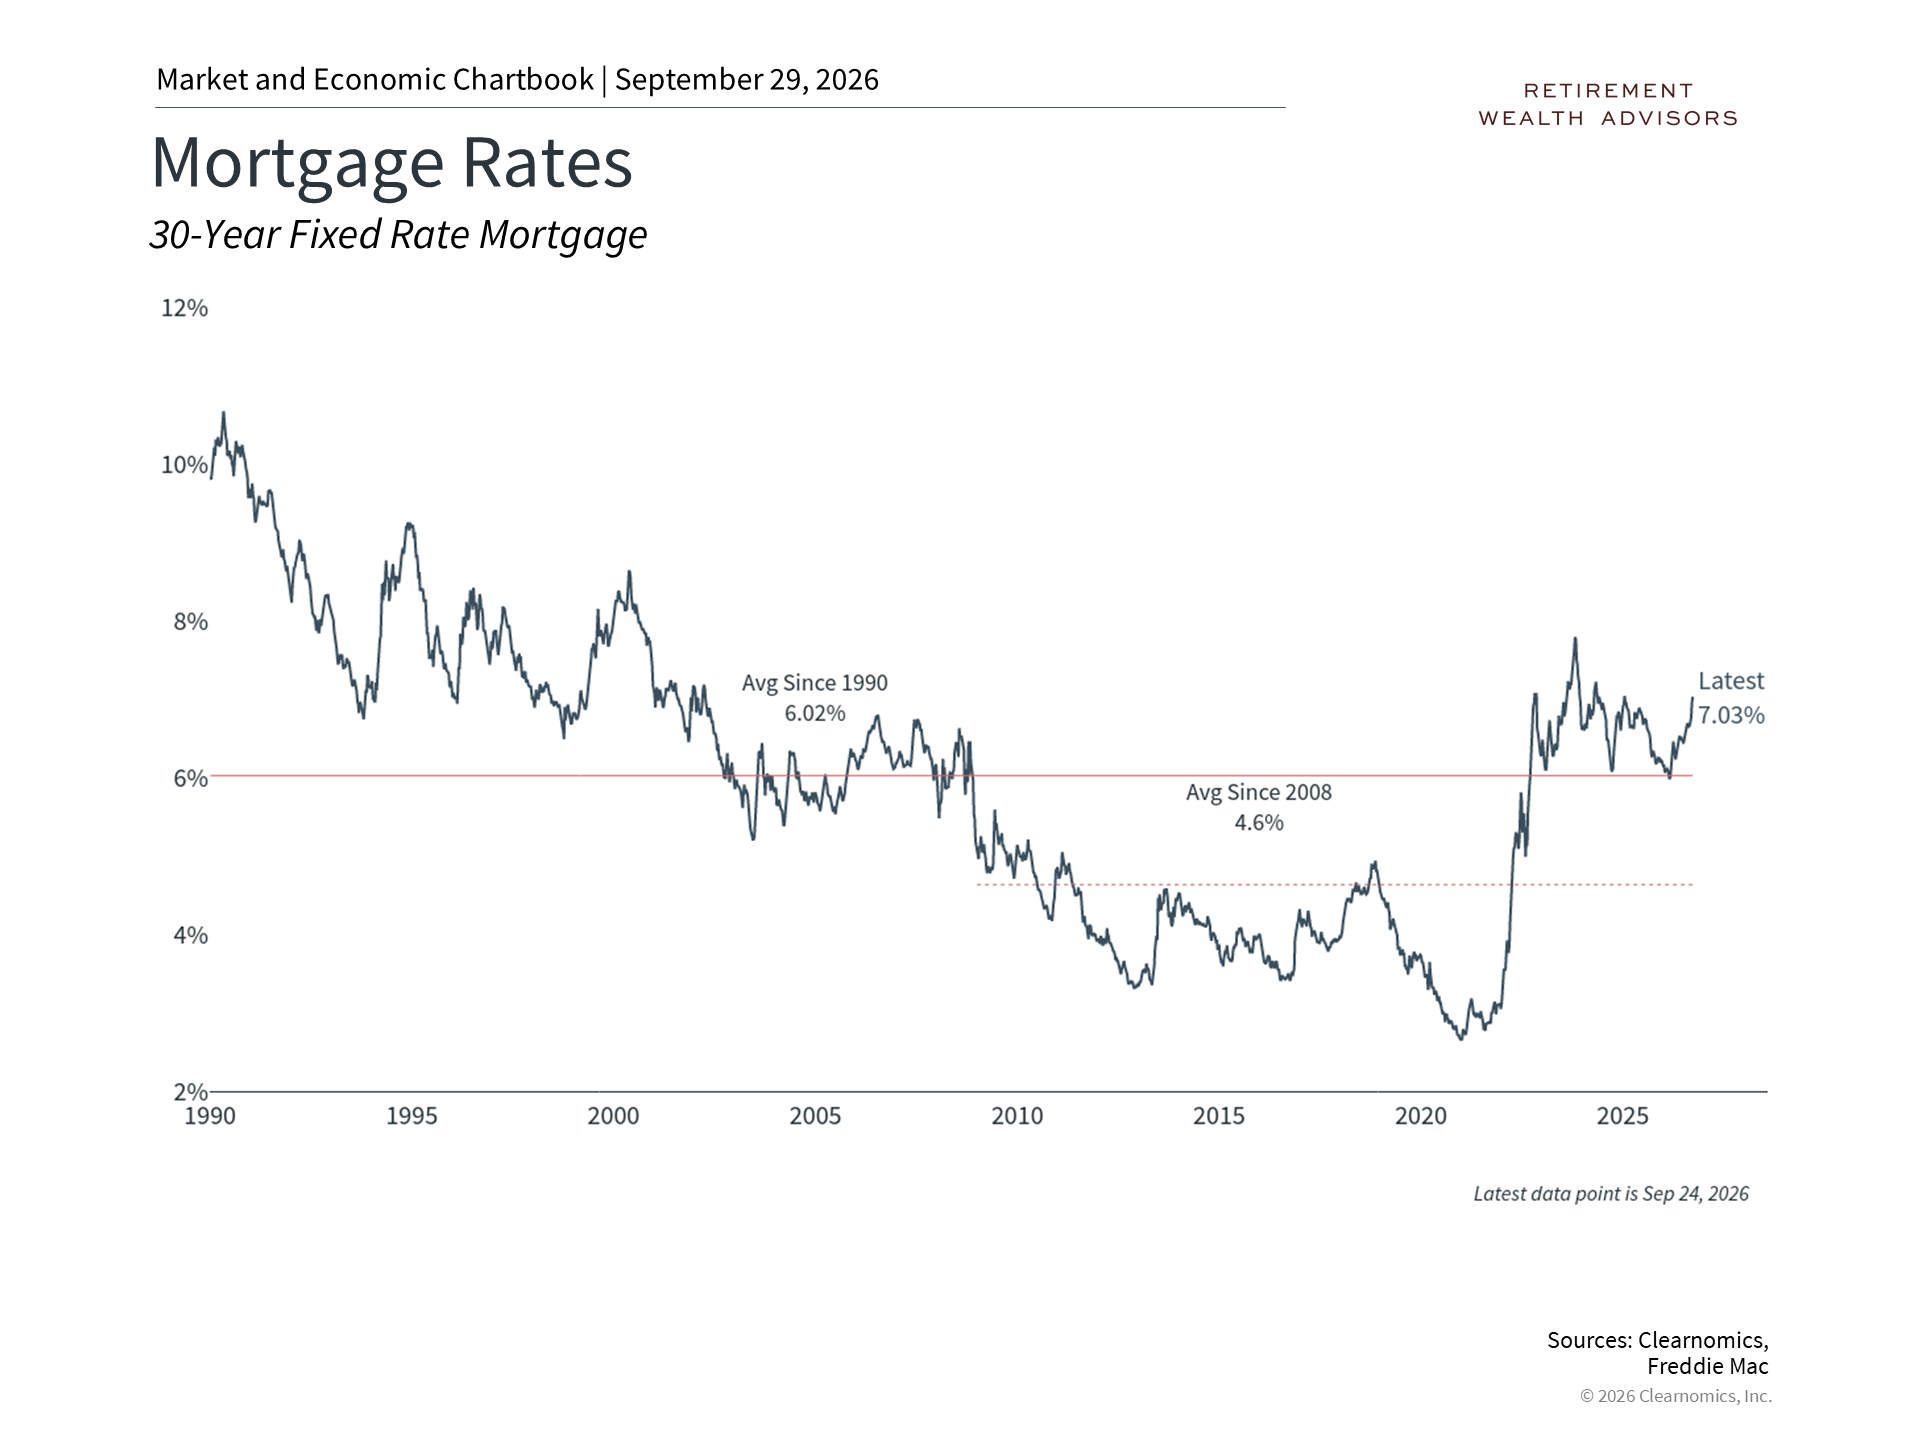
Mortgage rates had been falling alongside long-term government bond yields from the early 1980s all the way to 2020, when they hit their lowest point during the pandemic. Between 1990 and the 2008 financial crisis, the typical 30-year fixed mortgage rate averaged around 6%. After 2008, that average dropped to just 4.6%. During the pandemic years, when rates fell to 3% or even lower, many buyers and homeowners got used to very affordable borrowing costs that were well below what had been normal historically.
The return to 7% raises real questions about whether buying a home still makes financial sense for many people. One of the biggest side effects is what economists call the "lock-in" effect. Homeowners who locked in low rates on their mortgages years ago have little reason to sell, because selling would mean taking out a new mortgage at today's much higher rate. This reduces the number of homes available for sale, which keeps the number of home sales low. In fact, policymakers in Washington are exploring ideas like "portable mortgages" that would let homeowners carry their lower rate with them when they move to a new home.
According to the National Association of Realtors, existing home sales (sales of homes that have been owned before) fell 2.0% from the prior month and 1.2% compared to the same time last year in August, showing that the market remains slow.2 The amount of existing homes available for sale now equals about 4.9 months of supply, while new homes represent 8.5 months of supply, the highest levels seen in over a decade.3 While having more homes available is generally a good thing for buyers, these figures are based on how quickly homes are selling, so they may simply reflect homes sitting on the market longer without finding buyers.
For those who do decide to buy, higher mortgage rates directly make homes less affordable. A bigger portion of monthly income must go toward paying the mortgage. This gives many potential buyers a reason to wait and see if rates improve, which delays housing activity even further and forces tough choices about location, home size, or how much to put down as a deposit.
Despite slow sales activity, home prices remain near record highs
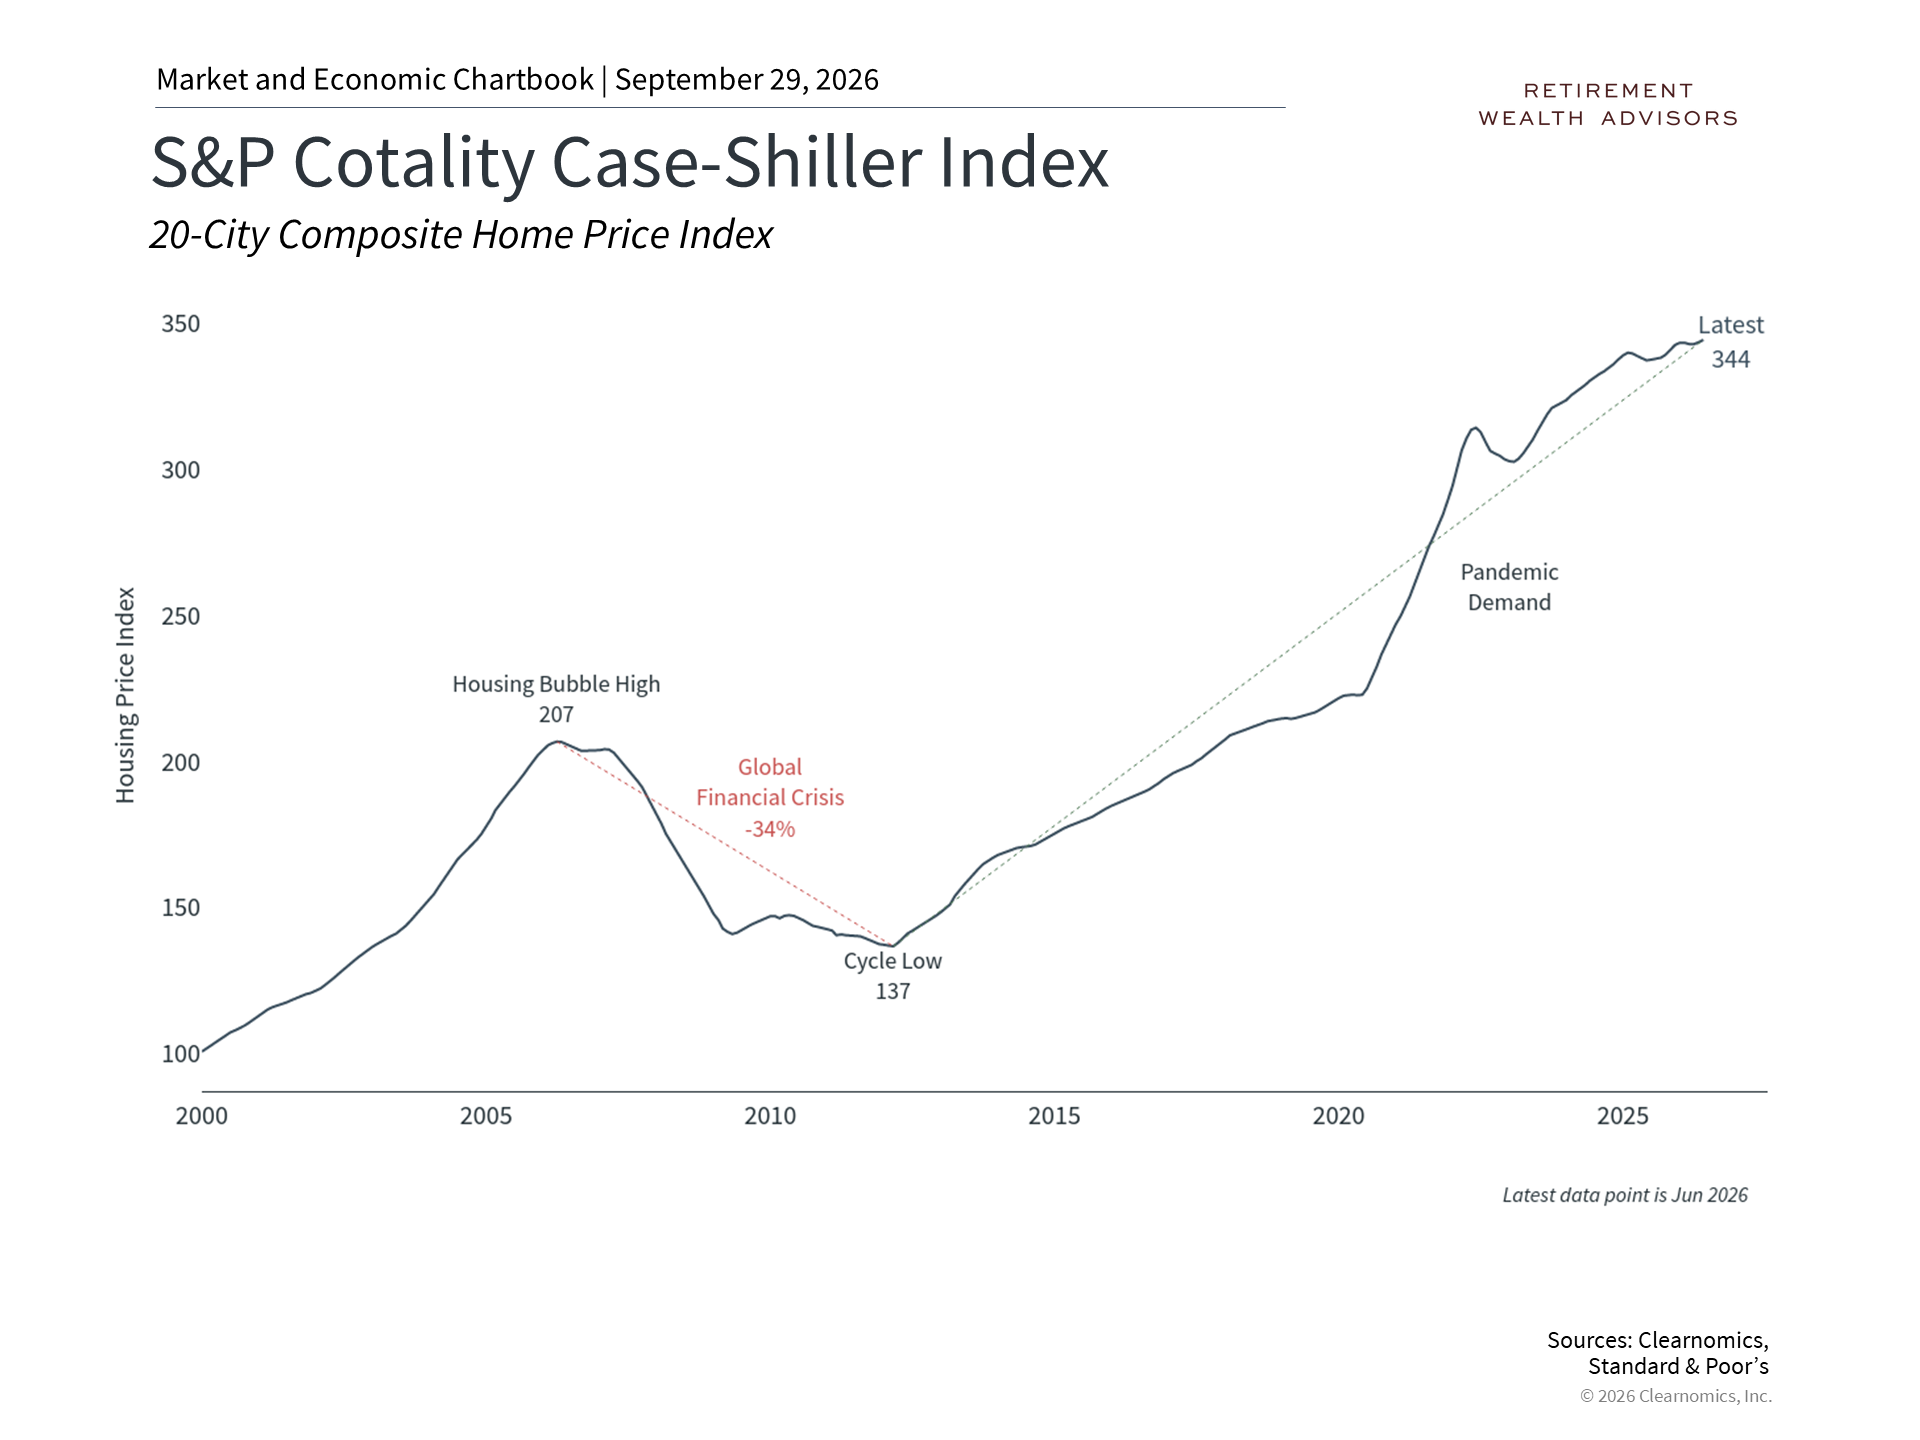
Even though the number of home sales is low, home prices across the country remain near record highs according to the S&P Cotality Case-Shiller Index, as shown in the chart above. It is not unusual for the number of sales and the level of prices to move in opposite directions. The overall economy is still in good shape and unemployment (the share of people without jobs) is low. This means most current homeowners can afford to keep paying their mortgages and stay put, even if they have no urgent reason to move.
High home prices on paper also create what is often called the "wealth effect." When homeowners see that their home is holding its value or going up in price, they tend to feel more financially secure. Combined with the stock market sitting near all-time highs, these trends can encourage people to spend more on goods and services.
This may partly explain why consumer spending has held up better than many economists expected, even with concerns such as tariffs and higher energy costs. This is true even though consumer sentiment (how people say they feel about the economy) has stayed near historic lows. One of the puzzles of recent years is the gap between how gloomy people say they feel about the economy and how much they are actually spending.4
One explanation is that sentiment is more driven by inflation (rising prices), which is pushed up by things like higher gasoline prices, while actual spending is supported by the wealth effect from rising home and stock values. Housing costs make up more than one-third of the Consumer Price Index (a measure of overall price levels), but "shelter" costs have risen only 3% over the past year, while gasoline prices have jumped 27.4%.5
Refinancing activity has dropped sharply
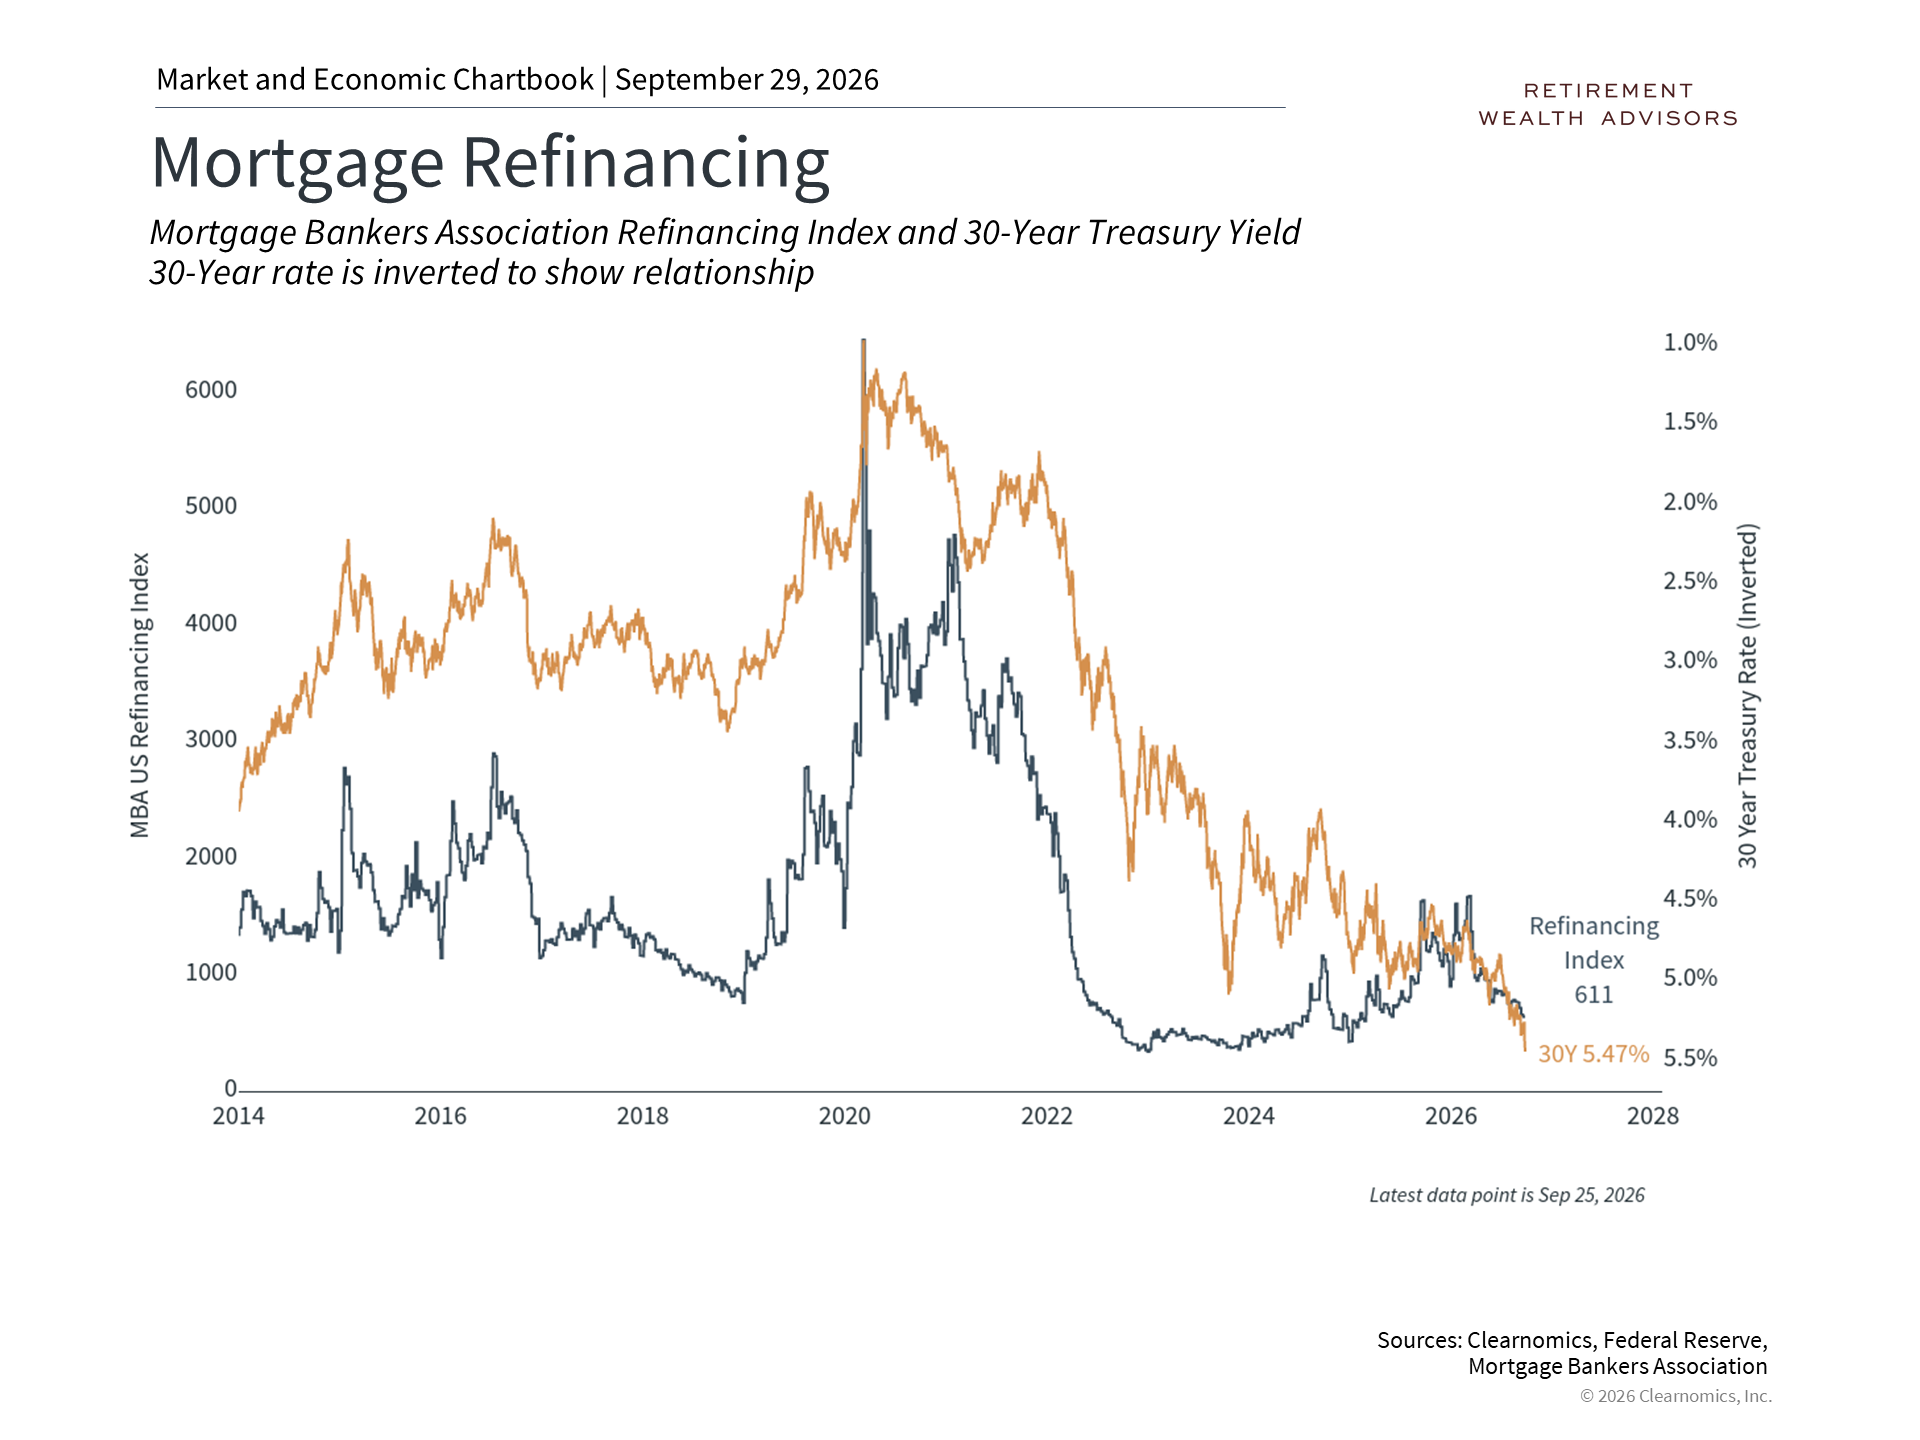
As interest rates have risen, it makes sense that refinancing activity has also dropped sharply. Refinancing means replacing your existing mortgage with a new one, usually to get a lower rate or to take cash out of your home's value. Data from the Mortgage Bankers Association shows that the volume of refinancing has fallen to multi-year lows after peaking between 2020 and 2022, when many homeowners took advantage of historically low rates to cut their monthly payments or access their home equity (the portion of the home's value they actually own).6
In practical terms, homeowners who might have refinanced to access cash from their rising home values are no longer able to do so at attractive rates. Since refinancing is one of the main ways households turn rising home values into money they can spend, this could weigh on consumer spending going forward.
Mortgage debt remains by far the largest type of borrowing for most households, even as credit card and student loan balances have grown in recent years. Household debt service as a share of disposable income (the percentage of take-home pay that goes toward paying debts) stood at about 11% in the second quarter of this year. This is still moderate compared to the pre-2008 peak of nearly 16%, which suggests that most households are managing their debt load reasonably well, even if they cannot tap into their home equity.7
The effect on spending, home prices, and sales activity will depend largely on how long interest rates stay elevated. Right now, many interest rates are near twenty-year highs across different time periods, including 5-year, 10-year, and 30-year U.S. Treasury bond yields.8 With inflation remaining stubbornly above the Federal Reserve's target level, bond markets suggest rates may stay higher for longer. The Fed's own quarterly Summary of Economic Projections indicates that policy rates (the short-term rates the Fed controls) could remain elevated through at least 2027.9 While predicting exactly where rates will go is difficult, especially if there are new developments with inflation, oil prices, or the job market, investors and households are best served by staying disciplined and sticking to their long-term financial plans.
The bottom line? The housing market is likely to keep feeling the effects of elevated interest rates as mortgage rates stay above 7%. For investors, this environment of higher rates calls for staying attentive and keeping a focus on long-term financial planning.
References
2. https://www.nar.realtor/newsroom/nar-existing-home-sales-report-shows-2-0-decrease-in-august
3. https://www.nar.realtor/research-and-statistics/housing-statistics/existing-home-sales
4. https://www.sca.isr.umich.edu/
5. https://www.bls.gov/news.release/cpi.nr0.htm
6. Clearnomics research and the Mortgage Bankers Association, as of September 28, 2026
7. Clearnomics research and the Federal Reserve Economic Data, as of September 28, 2026
8. https://home.treasury.gov/policy-issues/financing-the-government/interest-rate-statistics
9. https://www.federalreserve.gov/monetarypolicy/fomcprojtabl20260916.htm
Index Descriptions
S&P Cotality Case-Shiller Home Price Indices
The S&P Cotality Case-Shiller 20-City Index measures the value of residential real estate and tracks changes in the selling prices of single-family homes across 20 major U.S. metropolitan areas.
Copyright (c) 2026 Clearnomics, Inc. All rights reserved. The information contained herein has been obtained from sources believed to be reliable, but is not necessarily complete and its accuracy cannot be guaranteed. No representation or warranty, express or implied, is made as to the fairness, accuracy, completeness, or correctness of the information and opinions contained herein. The views and the other information provided are subject to change without notice. All reports posted on or via www.clearnomics.com or any affiliated websites, applications, or services are issued without regard to the specific investment objectives, financial situation, or particular needs of any specific recipient and are not to be construed as a solicitation or an offer to buy or sell any securities or related financial instruments. Past performance is not necessarily a guide to future results. Company fundamentals and earnings may be mentioned occasionally, but should not be construed as a recommendation to buy, sell, or hold the company's stock. Predictions, forecasts, and estimates for any and all markets should not be construed as recommendations to buy, sell, or hold any security--including mutual funds, futures contracts, and exchange traded funds, or any similar instruments. The text, images, and other materials contained or displayed in this report are proprietary to Clearnomics, Inc. and constitute valuable intellectual property. All unauthorized reproduction or other use of material from Clearnomics, Inc. shall be deemed willful infringement(s) of this copyright and other proprietary and intellectual property rights, including but not limited to, rights of privacy. Clearnomics, Inc. expressly reserves all rights in connection with its intellectual property, including without limitation the right to block the transfer of its products and services and/or to track usage thereof, through electronic tracking technology, and all other lawful means, now known or hereafter devised. Clearnomics, Inc. reserves the right, without further notice, to pursue to the fullest extent allowed by the law any and all criminal and civil remedies for the violation of its rights.
Author: Eric Kearney
Recognized as S.W. Florida’s Premier Investment Advisor, Eric Kearney with Retirement Wealth Advisors LLC has been helping clients reach and maintain their financial goals since 2001.
